How Much Should I Actually Be Saving?
It's one of those questions that sounds as though it should have a simple answer.
How much of my income should I be saving?
You may have heard rules about saving 10%, 20% or some other magic number. But your life isn't a formula.
Someone saving for a first home has different priorities from someone paying down debt, starting a family or simply trying to build a little breathing room.
So perhaps the better question isn't, "What percentage should I save?"
It's, "What am I saving for?"
Start With A Buffer
Before thinking about big financial goals, it can help to have some money available for the things you didn't plan.
The car repair. The unexpected bill. A period between jobs.
How much you need will depend on your circumstances, but the principle is simple: having a buffer means an unexpected expense doesn't automatically become new debt.
You don't have to build it overnight. Consistency matters more than perfection.
Give Your Savings A Job
Saving becomes much easier when the money has a purpose.
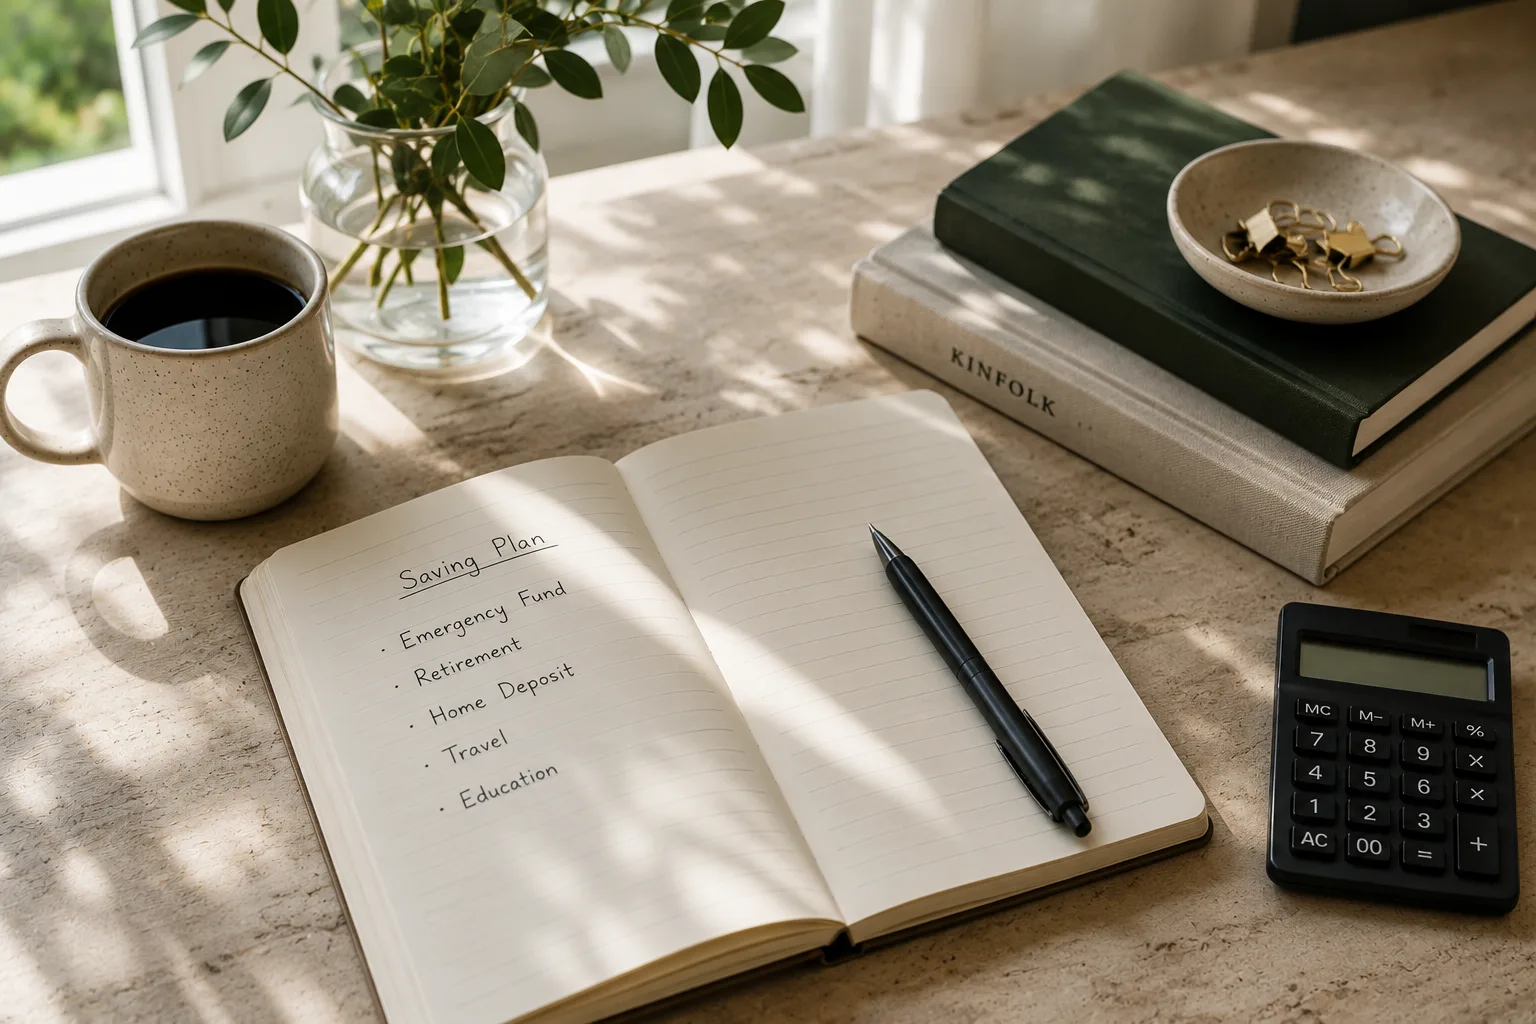
Instead of one account called "savings", you might be working towards several things.
A home deposit. A holiday. Education. A new car. Starting a business.
Once you know what you're saving for, you can work backwards from the amount you need and when you'd like to have it.
Suddenly, saving becomes less abstract.
Make It Happen Automatically
One of the simplest ways to build savings is to remove the need to make the decision every payday.
Automating a regular transfer means you're paying your future self before the money disappears into everyday spending.
The amount doesn't need to be enormous.
A realistic amount you can maintain is generally more useful than an ambitious target you abandon after two months.
Saving Isn't Always The Only Answer
There may come a point where keeping every spare dollar in cash isn't necessarily the best use of your money.
Depending on your goals, timeframe and circumstances, you may want to consider whether some money could be used to reduce debt, contribute to super or invest for longer-term goals.
The right balance will be different for everyone.
That's why understanding what you're trying to achieve comes first.
Don't Forget To Enjoy Today
Being good with money shouldn't mean putting your entire life on hold.
There is a balance between preparing for tomorrow and enjoying today.
A financial plan that leaves no room for holidays, dinners, hobbies or the things you value probably isn't a plan you'll stick to.
The aim isn't simply to save more.
It's to use your money more deliberately.
One Final Thought
Don't worry too much about whether you're saving the "right" percentage.
Start with an amount that works for you. Give it a purpose. Make it consistent. Then increase it when your circumstances allow.
A Question Worth Asking Yourself Today
If you looked at your savings today, could you clearly say what you're saving for?